
Vriddhi: taking a co-operative bank's loans from paper files to a 48-hour digital journey
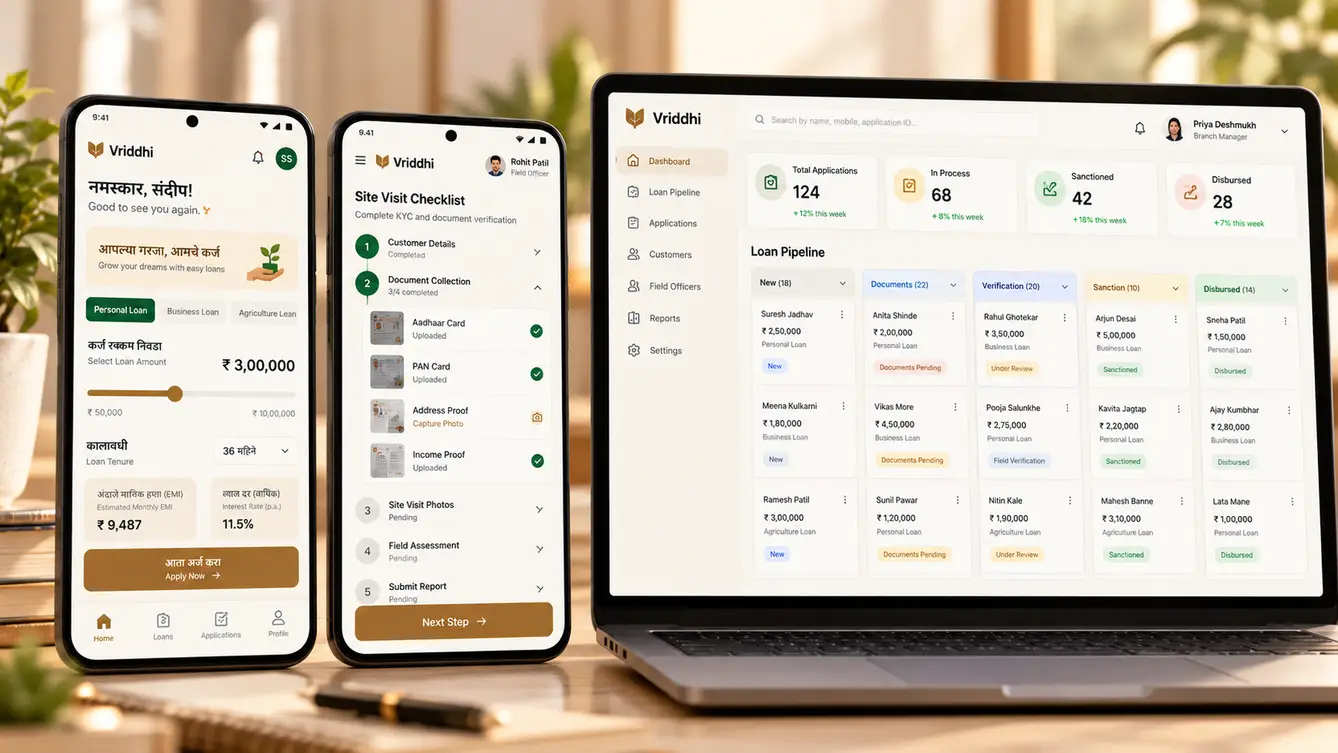
A co-operative bank with branches across small towns wanted to compete with fintech lenders without losing the branch relationships its members trusted. We built Vriddhi: a member app, a field-officer app and a branch loan-origination system, connected to the bank's existing core banking — 27 features, designed around the loan officer rather than around the software.
Why a 60-year-old bank called us
Vriddhi's chairman had watched members walk out of his branches with loan offers on their phones. Not because the bank's rates were worse — they were often better — but because a fintech app promised an answer in minutes, and the bank's own process took three weeks, four branch visits and a file thick enough to use as a doorstop.
The bank's strength was trust and local knowledge. Loan officers knew their members' families and businesses. What they lacked was a way to capture that knowledge digitally, move a file without physically carrying it, and give the member any idea of where their application stood.
“Our members don't want a faster bank. They want to know what is happening with their loan.”
Three days in a branch
We started by spending three full days in two branches, one busy town branch and one rural branch. We followed loan files from counter to sanction. A typical file passed through nine hands. Documents were photocopied three times. The biggest delay was not credit assessment — it was waiting: for a missing document, for a signature from the branch manager, for the file to travel to the regional office.
We also saw what could not change. Many members were more comfortable in Marathi than English, preferred to speak to their officer in person, and did not trust anything that asked for their bank password. The design had to respect all of that.
- Chasing missing documents: the single biggest delay
- Physical file movement between branch and regional office
- Re-keying the same data into the core banking system
- Members calling the branch to ask for status
The shape of the product
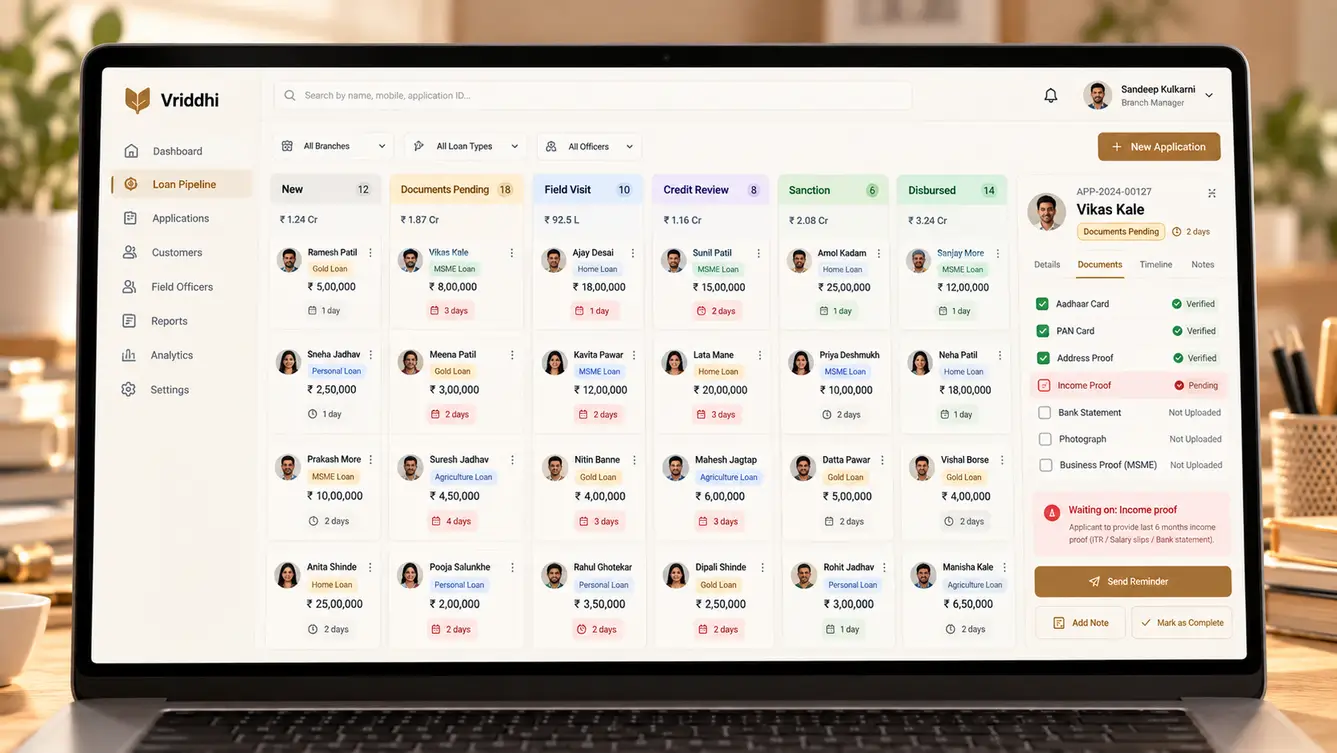
We designed three connected products around one loan file. Members could apply, upload documents and track status in an app. Field officers got an app for doorstep visits: capture documents, photos of the business or property, and their own assessment notes, even offline. Branch staff got a web loan desk where the file moved through stages with clear owners and deadlines.
Critically, Vriddhi did not replace the core banking system. It sat in front of it: collecting, checking and approving applications, then posting sanctioned loans into the core system through an integration layer, so the bank's accounting stayed exactly where its auditors expected it.
The team
Integration with a legacy core banking system was the riskiest part, so we put a senior integration engineer on the project from the first week, working directly with the bank's IT vendor.
IT committee reviews, branch pilots and rollout planning.
Bilingual member app, field app and loan desk workflows.
Member and field-officer apps with offline document capture.
Branch loan desk and head-office console.
Loan workflow engine, rules and document service.
Core banking integration layer and Account Aggregator.
End-to-end loan scenarios and security testing.
9 people in total, working as one team.
Decisions that shaped Vriddhi
Banks are rightly conservative, so every major decision went to the bank's IT committee with the options and our recommendation.
Replace the core banking system or sit in front of it?
- Migrate to a new core
- Build a digital layer in front of the existing core
Our call: Build a digital layer in front of the existing core. A core migration is a multi-year risk. Sitting in front of it delivered the member experience quickly while keeping accounting where auditors and regulators expect it.
How to verify income?
- Ask for bank passwords
- Manual statement uploads only
- Consent-based Account Aggregator with upload fallback
Our call: Consent-based Account Aggregator with upload fallback. Account Aggregator gives verified statements with explicit member consent and never touches credentials; uploads remain for members who prefer them.
Where to host?
- Public cloud
- Bank's own data centre
- Hybrid: apps in private cloud, core integration on-premise
Our call: Hybrid: apps in private cloud, core integration on-premise. Member-facing apps needed to scale; core banking data had to stay within the bank's controlled environment. A hybrid met both requirements and the bank's IT policy.
Automate credit decisions?
- Fully automated scoring
- Rule-based checks plus officer judgement
Our call: Rule-based checks plus officer judgement. The bank's advantage was local knowledge. Automated checks catch policy breaches and missing data; the decision stays with the officer and branch manager.
Offline support for field officers?
- Online only
- Offline-first with encrypted local storage
Our call: Offline-first with encrypted local storage. Many doorstep visits happen with no signal. Documents and notes are captured offline, encrypted on the device and synced when the officer is back in coverage.
The 27 features
Everything below shipped in the first full release, across the member app, field app, branch loan desk and head-office console.
- 01Loan eligibility check
Instant indicative eligibility and EMI for each loan product.
- 02Digital application
Bilingual application forms with saved progress.
- 03Document upload with guidance
Camera capture with checks for blur and cropping.
- 04Live application status
Every stage, what it is waiting for and who owns it.
- 05EMI schedule and repayments
Upcoming EMIs, history and UPI repayment.
- 06Visit planner
Daily visit list with map routing.
- 07Offline document capture
Encrypted capture and sync when back online.
- 08Geo-tagged site photos
Business and property photos with location and time.
- 09Officer assessment notes
Structured notes and recommendations on each file.
- 10Full file viewer
Every document and note available at the doorstep.
- 11Loan pipeline board
Every file by stage with owners and ageing.
- 12Automatic document reminders
SMS and WhatsApp nudges to members for missing documents.
- 13Policy rule checks
Automatic checks for eligibility, limits and exposure.
- 14Digital sanction workflow
Approvals by delegation of power, with digital sign-off.
- 15Sanction letter generation
Bilingual sanction letters from templates.
- 16Account Aggregator statements
Consent-based bank statement retrieval.
- 17KYC verification
Identity checks against official sources with CKYC lookup.
- 18Document OCR
Extract key fields from income and property documents.
- 19Duplicate application detection
Flags repeat applications across branches.
- 20Core banking posting
Sanctioned loans posted to the core system automatically.
- 21Portfolio dashboards
Applications, approvals and turnaround by branch and product.
- 22Turnaround-time tracking
Time spent in each stage, per branch.
- 23Role-based access and delegation
Permissions aligned with the bank's powers matrix.
- 24Complete audit trail
Every view, edit and approval recorded for inspection.
- 25Product configuration
Head office configures loan products and rules without code.
- 26Regulatory reports
Exports in the formats the bank's reporting requires.
- 27Member communication log
All messages to a member in one timeline.
Rollout: branch by branch
We piloted Vriddhi in the two branches where we had done discovery. Officers kept paper files as a fallback for the first month, and our engagement lead held a short daily call with each branch manager. The biggest early lesson was that officers needed to see the whole file on their phone at a member's doorstep; we moved the full document viewer into the field app in the second week of the pilot.
The remaining branches came on in three waves, each preceded by a training session in Marathi run by the pilot branch officers themselves — which did more for adoption than anything we could have said.
- Weeks 1–3Discovery
Three days in two branches, loan files traced end to end, IT policy review.
- Weeks 4–7Design and integration spike
Bilingual prototypes tested with officers; core-banking integration proven early.
- Weeks 8–16Build
Member app, field app, loan desk and integration layer in two-week sprints.
- Weeks 17–19Pilot
Two branches live with paper fallback and daily check-ins.
- Weeks 20–24Rollout
Remaining branches in three waves, trained by pilot-branch officers.
What we learned
Digitising a bank is mostly about removing waiting, not speeding up work. Status visibility, automatic document reminders and digital file movement did more than any clever credit model.
The best trainers were the bank's own staff. Once officers in the pilot branches were fluent, they taught their colleagues in their own language, with their own examples.
- React Native
- Next.js
- Java / Spring Boot integration layer
- PostgreSQL
- Document OCR
- Account Aggregator APIs
- On-premise + private cloud
